

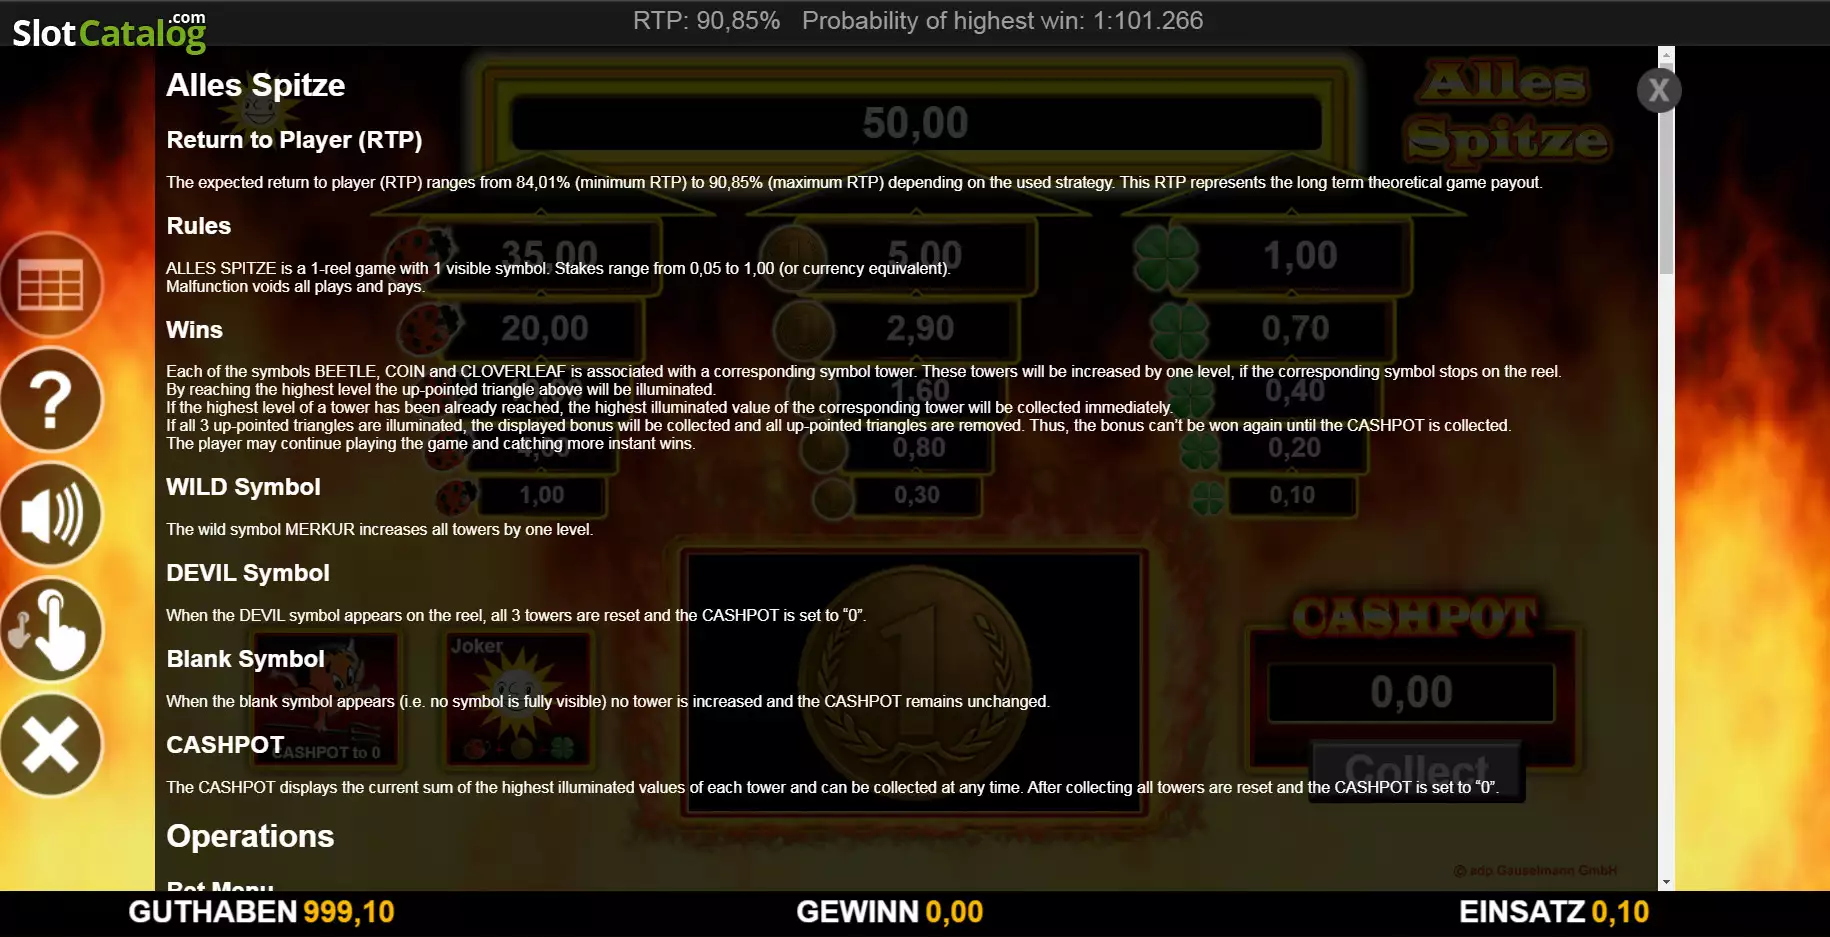
As we steer our financial paths, the idea of post-work planning can commonly feel like a far-off and intricate challenge https://allesspitze.eu/. We recognize the need to create a solid financial buffer for our retirement years, yet the path to achieving real future protection in the UK demands more than just standard pension payments. In today’s landscape, we must adopt a integrated method that aligns prudent, long-term investments with the responsible management of our today’s assets and recreational pursuits. This encompasses comprehending how contemporary amusement, such as virtual gaming activities similar to those from Alles Spitze Slot, belongs within a broader, balanced lifestyle. Our aim here is to investigate the core fundamentals of a safe retirement while acknowledging the complete range of our financial habits, making sure we build a future that is both economically robust and emotionally rewarding, without compromising on current balanced pleasure.

Understanding the UK Retirement Terrain
The system for post-work in the United Kingdom is founded on a complex system, and grasping its intricacies is our initial move for efficient preparation. Essentially lies the State Pension, a cornerstone provided by the state, but its completeness for a comfortable living is commonly challenged. To close this gap, workplace superannuation have become automatic for the majority of workers, with payments from both the organization and the person creating a essential secondary layer. Moreover, individual pensions and Individual Savings Accounts (ISAs) provide us additional versatility and command over our investment options. Nonetheless, the scene is always evolving because of elements like rising longevity, policy alterations, and market volatility. This implies our pension plan must not remain fixed; it requires regular review and modification. We need to actively participate with these parts, grasping their pros and cons, to build a post-work plan that is not only abiding by the established structure but optimised for our individual goals and expected requirements in our later years.
Risk Control in Long-Term Investments
When putting money for a goal far in the future, like retirement, comprehending and controlling risk is paramount. Risk, in an investment context, is not necessarily negative; it is the source of future gains. However, poorly handled risk can lead to instability that may jeopardise our plans. Our main tool for risk management is investment allocation—the deliberate distribution of our investments across diverse categories. Typically, when we are younger, we can manage to have a larger proportion of growth-oriented assets like equities, as we have time to bounce back from market downturns. As we get closer to retirement, the strategy should gradually shift towards protecting capital, including more steady, yielding assets like bonds. It’s also important to diversify within each asset class, distributing investments across various sectors and regional regions. We must regularly readjust our portfolio to uphold our desired risk level and avoid emotional decision-making during market swings, adhering to our long-range data-driven strategy.
The Cornerstones of a Secure Retirement Plan
Building a reliable retirement is comparable to building a sturdy house; it requires multiple, well-anchored pillars. The first and most important pillar is consistent and early saving. The power of compound interest ensures that even modest, regular contributions made over decades can grow into a substantial sum, far exceeding larger sums saved later in life. The second pillar is spreading risk. We should never count on a single investment or pension pot. A healthy portfolio distributes risk across different asset classes, such as stocks, bonds, and property, adjusting its balance as we move closer to retirement age. The third pillar is debt management. Entering retirement burdened by significant high-interest debt can severely reduce our monthly income. Therefore, a forward-thinking strategy to reduce and eliminate debts, particularly mortgages and credit card balances, is integral. Finally, the fourth pillar is planning for healthcare and potential long-term care costs, which are often overlooked. Together, these pillars form a robust structure that can support us through a retirement that may span thirty years or more.
Planning for Tomorrow While Enjoying Today
A common issue we face is balancing the imperative to save for the future with the desire to enjoy our present lives. The key lies not in deprivation, but in mindful budgeting and deliberate spending. We start by creating a clear and honest budget that tracks our income against essential outgoings, savings commitments, and discretionary spending. This process highlights where our money goes and pinpoints potential areas for reallocation. It’s perfectly understandable, and indeed healthy, to allocate funds for leisure and entertainment, such as dining out, hobbies, or digital subscriptions. The principle is to treat these as planned expenses rather than unplanned purchases. By setting aside our retirement savings as a non-negotiable monthly outgoing—much like a utility bill—we ensure our future security is given priority. What remains is ours to use wisely, allowing us to relish today’s experiences without guilt, knowing our long-term plan remains securely on track.
Tools and Resources for UK Savers
Thankfully, we are not by ourselves in navigating retirement planning. A range of tools and resources is accessible to UK savers to aid our journey. The government’s free Pension Wise service delivers priceless guidance for those over 50 nearing retirement. Online pension calculators, supplied by many financial institutions and independent bodies, help us to estimate our potential pension income based on current savings rates. Budgeting apps have become advanced allies, helping us to track spending and savings goals with ease. For investment education, resources from the MoneyHelper service and the Financial Conduct Authority (FCA) offer unbiased, trustworthy information. Furthermore, seeking professional independent financial advice, while an expense, can be a very worthwhile investment, delivering personalised strategies and peace of mind. Leveraging these tools empowers us to make informed decisions, demystifies complex products, and holds us engaged with our long-term financial health.
The Place of Modern Entertainment in Financial Wellbeing
Financial wellbeing is a holistic state that encompasses not just the stability of our bank balance, but also our mental and emotional health. Responsible leisure and entertainment play a substantial role in this equation. Engaging in enjoyable activities provides necessary stress relief, social connection, and cognitive stimulation, all of which contribute to a balanced life. In the digital age, this includes online entertainment platforms. The critical factor is integration, not exclusion. We advocate for a framework where such activities are enjoyed within clear personal boundaries regarding time and expenditure. Setting strict deposit limits, viewing any spending as a cost for entertainment (similar to a cinema ticket) rather than an investment, and prioritising it only after essential bills and savings are covered, are unavoidable practices. When managed with this disciplined mindset, modern entertainment can coexist with robust financial health, adding colour to our daily lives without dimming our future prospects.
Frequent Retirement Planning Mistakes to Evade
On the path to retirement security, several pitfalls can derail even the best-intentioned plans. One of the most common mistakes is simply beginning too late, drastically diminishing the advantage of compound growth. Another is misjudging life expectancy and consequently saving too little, contributing to a gap in our later years. We often see an over-reliance on the State Pension or a single pension plan, missing the variety needed for resilience. Neglecting to regularly evaluate and revise our plan is another critical error; life conditions, laws, and economic conditions change, and our strategy must evolve with them. Emotion-driven investment choices, such as panic-selling during a market decline or chasing high-risk trends, can inflict lasting damage on a portfolio. Lastly, overlooking to plan for inflation’s corrosive effect on purchasing power can leave us with a nominal sum that purchases far less than expected. Knowledge of these common errors is our first line of defence against them.
Adapting Your Plan to Life’s Changes
A retirement plan is not something we draft and forget; it is a evolving strategy that must adjust to the certain changes in our lives. Key life events such as marriage, having children, changing careers, receiving an inheritance, or facing illness all have deep financial implications. Each of these milestones demands a review of our goals, risk tolerance, and savings capacity. For instance, starting a family may briefly reduce our disposable income for saving but heightens the long-term need for security. A career change might come with a more generous employer pension contribution. Furthermore, larger economic changes like interest rate shifts or new pension legislation introduced by the government require us to reconsider our approach. We suggest a formal review of our entire retirement plan at least annually, and immediately following any major life event, to ensure it continues to align with our evolving circumstances and aspirations.
Establishing an Inheritance and Property Succession Issues
While guaranteeing our own comfort is the principal goal, many of us also wish to transfer a financial inheritance to family members or causes we care about. This highlights the important area of estate preparation. Effective legacy development involves more than just possessing wealth; it necessitates clear legal frameworks to ensure our desires are carried out effectively. Key measures include preparing a valid will, which is the bedrock of any estate arrangement, specifying exactly how our assets should be divided. We should also evaluate the potential implications of Inheritance Tax (IHT) and investigate legitimate methods for minimization, such as gifting allowances and trusts, often with specialist guidance. Furthermore, ensuring our pension death benefit assignments are up to date is vital, as pensions often lie beyond the estate for IHT reasons. By handling these factors preemptively, we can not only protect our own future but also establish a purposeful and effective passing of wealth, benefiting future generations and leaving a lasting, positive impact.